

Backdoor Roth IRA Strategy
What Is a Backdoor Roth?
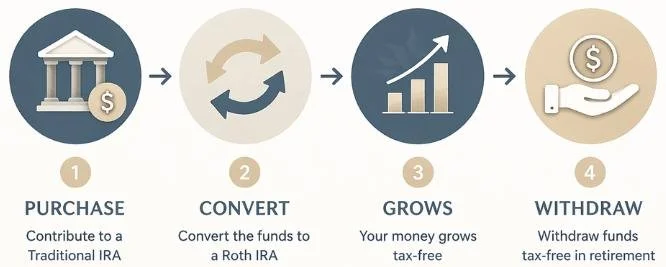
A Backdoor Roth is a conversion strategy that allows individuals to contribute to a Roth IRA by first contributing to
a Traditional IRA and then converting those funds into a Roth IRA.
Why This Matters
By building assets in a Roth IRA, investors create a pool of funds that can grow and be withdrawn tax-free in retirement,
helping manage future tax uncertainty. This can be especially valuable for tax planning, as it provides flexibility to control
taxable income in retirement years. From a legacy perspective, Roth assets can be passed to heirs’ income tax-free,
making them an efficient way to transfer wealth. Additionally, having a mix of taxable, tax-deferred, and tax-free assets
allows for more strategic withdrawal planning, helping preserve wealth and support long-term financial goals
• Tax-free growth
• Tax-free withdrawals in retirement
• No required minimum distributions (RMDs)
• Greater flexibility in retirement income planning
Timing can be Important
Roth conversions are often most effective in lower-income years—such as before Social Security begins, after retirement
but before required minimum distributions (RMDs), or during a temporary drop in income—with the goal of filling lower tax
brackets (such as 22%–24%) to improve long-term tax efficiency. The main goal here would be to fill lower tax brackets
(22% / 24%).
Our Role
• Determine if strategy could be beneficial (Financial Planning)
• Coordinate with your CPA – It can be a taxable event
• Ensure proper execution and reporting (Form 8606)
Disclosures
This summary is being provided as a service to you by Patron Partners. In preparing this report, Patron Partners has relied upon information provided
by the account custodian. You should be receiving statements at least quarterly from your custodian. If you are not receiving these statements, or you
need another copy, please call us and we will provide one to you. We encourage you to compare the information on the reports prepared by us
against the information in the statement(s) provided directly from your account custodian and to alert us of any discrepancies. Please remember to
contact Patron Partners if there are any changes in your personal/financial situation or investment objectives for the purpose of
reviewing/evaluating/revising our previous recommendations and/or services. Please also advise us if you would like to impose, add, or to modify any
reasonable restrictions to our investment advisor services. A copy of our current written disclosures statement discussing our advisory service and
fees continues to remain available for your review upon request.
Patron Partners, LLC, ("Patron") is a registered investment adviser with the United States Securities and Exchange Commission. Paton does not make any
representations or warranties as to the accuracy, timeliness, suitability, completeness, or relevance of any information prepared by Patron or any
unaffiliated third party. Patron is neither an attorney nor accountant, and no portion of the presented content should be interpreted as legal, accounting,
or tax advice. All such information is provided solely for convenience purposes only, and all users thereof should be guided accordingly.
